Markets · 3 Nov 2026Policy rateBank of Canada2.50%YieldsCA 2Y3.26%CA 5Y3.49%+3 bpCA 10Y3.77%+3 bpCanadian dollarCAD/USD0.7146−0.11%CAD/EUR0.6385−0.02%CAD/GBP0.5325−0.15%CAD/JPY113.25+0.34%CryptoBTCUS$80,404+3.69%ETHUS$2,430+5.97%

Morning Brief

Thursday 10 September 2026

Brent crude closed near US$101 a barrel on 9 September, its first close above US$100 since July, and this morning the European Central Bank raised rates by 25 basis points while U.S. producer prices came in at 5.4% over the year.

The desk’s view todayThe Bank of Canada holds at 2.25% through the autumn while the ECB and probably the Fed move up, keeping five-year fixed mortgage rates in the low-4% range and pushing the Canadian dollar lower.

Story 1 of 5

Oil closed above US$100 and bond yields hit a one-year high on the same day
A crude oil tanker under way at sea, illustrating the oil price move above US$100 a barrel
Photo: Thomas Timlen from Singapore, Singapore, CC0, via Wikimedia Commons

01What happened

Brent crude settled near US$101 a barrel on Wednesday 9 September, up about 3% on the day and above US$100 for the first time since July, after the U.S. Navy sank five Iranian tankers on Tuesday night and Iran said it had struck ten ships in the Strait of Hormuz in reply. WTI closed at US$95.39. The U.S. 10-year Treasury bond yieldBond yield The annual return an investor gets for lending to a government or company through a bond. Yields rise when bond prices fall. Fixed mortgage rates are priced from the 5-year Government of Canada yield. rose to 4.84% and the 2-year to 4.43%, both 52-week highs. Stocks fell: the S&P/TSX Composite lost 1.1% to 36,123, the S&P 500 0.5% and the Russell 2000 1.4%, while the TSX energy index gained 0.9%.

In Canada the 5-year Government of Canada yield, the one that sets fixed mortgage pricing, was 3.44% at Tuesday’s close, up 4 basis points on the day and about 25 basis points above where it sat a month ago. The 10-year was 3.81%, the 2-year 3.13%, and the dollar bought 72.47 U.S. cents. The national average pump price passed $1.80 a litre on Wednesday, with diesel already at a record, and the U.S. Energy Information Administration’s outlook published Tuesday expects Brent to hold near US$90 through the fourth quarter before easing toward US$74 in 2027.

02Our view

We think the 5-year Government of Canada yield stays above 3.3% through October unless the Strait of Hormuz reopens, which keeps five-year fixed mortgage rates in the low-4% range. We also think the U.S. government’s US$90 fourth-quarter oil forecast is the optimistic case, not the base case.

Why we think so. Markets have stopped treating the Hormuz disruption as a short interruption and started pricing it as a supply regime. Brent settled near US$101 on Wednesday, above US$100 for the first time since July, after the U.S. Navy sank five Iranian tankers and Iran said it had struck ten ships in reply. WTI closed at US$95.39. Bond investors then priced the inflation that follows: the U.S. 10-year Treasury bond yieldBond yield The annual return an investor gets for lending to a government or company through a bond. Yields rise when bond prices fall. Fixed mortgage rates are priced from the 5-year Government of Canada yield. rose to 4.84% and the 2-year to 4.43%, both 52-week highs. Canada followed. The 5-year yield, which sets fixed mortgage pricing, was 3.44% at Tuesday’s close, up 4 basis points on the day and about 25 basis points higher than a month ago. When both oil and yields rise together, the market is saying it expects higher prices to last, not fade.

What the market is pricing. The U.S. Energy Information Administration’s outlook, published Tuesday, expects Brent to hold near US$90 through the fourth quarter before easing toward US$74 in 2027. That assumes a gradual return to normal supply. We think it is the hopeful path while tankers are being sunk and diesel is already at a record. In the bond market, a 25 basis point rise over a month is roughly what separates a 4.1% five-year fixed quote from a 4.35% one, and we do not see the conditions for that move to reverse before the end of October.

What it means. A barrel above US$100 reaches the pump within two weeks and the grocery bill within two months, since diesel moves nearly everything that gets to a shelf; the national average pump price passed $1.80 a litre on Wednesday. Households who drive a lot should treat a fuel line 15% above last spring’s budget as the realistic number for the rest of the year. Borrowers with a renewal in the next 120 days can ask for a rate hold, which costs nothing and protects against the direction yields are moving. The bigger risk is stacking: transport, heating, a variable-rate loan and a renewal in the next year all move the same way in a week like this, so it is worth adding up how much of monthly spending is exposed to both energy and interest rates. For investors, energy-heavy portfolios gained while the S&P/TSX Composite fell 1.1% to 36,123.

What would change our mind. The strait reopening to normal traffic, Brent back under US$85 for two weeks, or a Fed hold on 16 September with U.S. CPI on Friday at or below 3% over the year. Any of these would let Canadian yields fall and push the 5-year below 3.3%.

What to watch. Today’s U.S. EIA crude inventory figures (consensus a draw of 1.4 million barrels) and 30-year bond auction, Friday’s U.S. consumer price index for August, the Federal Reserve on 16 September and the Bank of Canada on 29 October.

03Why it matters to you

If you have a mortgage renewal ahead, rising bond yields reach your fixed quote before the Bank of Canada moves. Comparing terms early gives you more room to choose.

Book a mortgage renewal review

Sources TheStreet, Stock Market Today (Sept. 9, 2026): Dow, Russell 2000 fall as Brent passes $101/bbl; Treasury yields set new 52wk highs; Yahoo Finance Canada, Stock market today: Dow, S&P 500, Nasdaq fall as Treasury yields climb, oil tops $100; WBUR, The Strait of Hormuz erupts as oil prices top $100; Yahoo Finance Canada, Canadian pump prices creep higher as Mideast fighting escalates; U.S. Energy Information Administration, Short-Term Energy Outlook, September 2026; Ascenthya market feed, Bank of Canada Valet data, 8 September close (yields) and 9 September (CAD)
Story 2 of 5

The ECB raised rates this morning, and U.S. producer prices are running at 5.4%

The European Central Bank headquarters tower in Frankfurt, Germany
Photo: Sfintu1, CC BY-SA 4.0, via Wikimedia Commons

01What happened

At 05:15 PT today the European Central Bank raised its three policy rates by 25 basis points, taking the deposit rate to 2.50%, effective 16 September. Its staff now project euro-area inflation of 3.0% in 2026 and 2.5% in 2027, and the statement says inflation will stay well above the 2% target for an extended period, with the Middle East conflict named as the reason. Fifteen minutes later the U.S. Bureau of Labor Statistics reported that the producer price index for final demand rose 0.4% in August and 5.4% over twelve months; the core measure excluding food, energy and trade was up 4.7% on the year. Diesel alone jumped 24.1% in the month and accounted for more than a third of the goods increase.

Futures markets were already pricing about a 60% chance that the U.S. Federal Reserve raises its own rate on 16 September. The Bank of Canada’s rate is 2.25%, unchanged since its 2 September hold.

02Our view

The ECB’s hike confirms that energy inflation has become a policy problem rather than a headline. We think a Fed hike on 16 September is now the more likely outcome, that the Bank of Canada holds at 2.25% through the autumn, and that the odds of a Canadian cut this year have fallen close to zero.

Why we think so. Two releases fifteen minutes apart told the same story. At 05:15 PT the European Central Bank raised its three policy rates by 25 basis points, taking the deposit rate to 2.50% from 16 September. Its staff now project euro-area inflation of 3.0% in 2026 and 2.5% in 2027, and the statement names the Middle East conflict as the reason inflation will stay well above target for an extended period. Then the U.S. producer price index rose 0.4% in August and 5.4% over twelve months, with the core measure up 4.7%. Diesel alone jumped 24.1% in the month. Producer prices are costs businesses pay before they set their own prices, so a 5.4% reading points to more consumer inflation ahead. Canada is in a different position: a 42,000 job loss in August and a U.S. import ban landing on 29 September argue against following the others up. The likely outcome is a widening gap between Canadian and foreign rates rather than a Canadian move in either direction.

What the market is pricing. Futures were already pricing about a 60% chance of a Fed hike on 16 September before the producer price report, and the ECB move matched expectations of a 2.50% deposit rate. We agree with the market on both and lean more firmly toward the Fed hiking. In Canada the consensus for 29 October is a hold at 2.25%, and we go further: we think a cut this year is now close to off the table.

What it means. For the first time since 2023, the two central banks that matter most for global bond prices are moving up, and Canadian fixed mortgage rates, GIC yields and the exchange rate follow North American and European yields before they follow Ottawa. Savers can lock a 1- to 2-year GIC at yields that now exceed inflation, which was not true a year ago. Borrowers face the other side of the same trade. The Canadian dollar, at 72.5 U.S. cents, is likely to weaken further if the Fed moves and the Bank of Canada does not, so anyone with U.S.-dollar expenses this winter, tuition or travel, may want to buy that currency in stages. For a retirement plan, a return assumption for the fixed-income portion set during the 2024 and 2025 cutting cycle is probably now too low.

What would change our mind. A Fed hold on 16 September with U.S. CPI on Friday at or below 3% over the year, or Brent back under US$85 for two weeks, would let Canadian yields fall and reopen the case for a Bank of Canada cut before year-end. A Canadian August CPI print above 3% would instead put a hike back on the table.

What to watch. The ECB press conference at 05:45 PT today, Friday’s U.S. consumer price index for August, the Federal Reserve on 16 September and the Bank of Canada on 29 October.

03Why it matters to you

If your savings include bonds, GICs or foreign holdings, rising global rates change what each is likely to earn. A review keeps your mix in step with that.

Book a portfolio review

Sources European Central Bank, Monetary policy decisions, 10 September 2026; U.S. Bureau of Labor Statistics, Producer Price Index News Release, August 2026; Yahoo Finance Canada, Stock market today: Dow, S&P 500, Nasdaq fall as Treasury yields climb, oil tops $100; Bank of Canada, Bank of Canada maintains the policy rate at 2¼%

Story 3 of 5

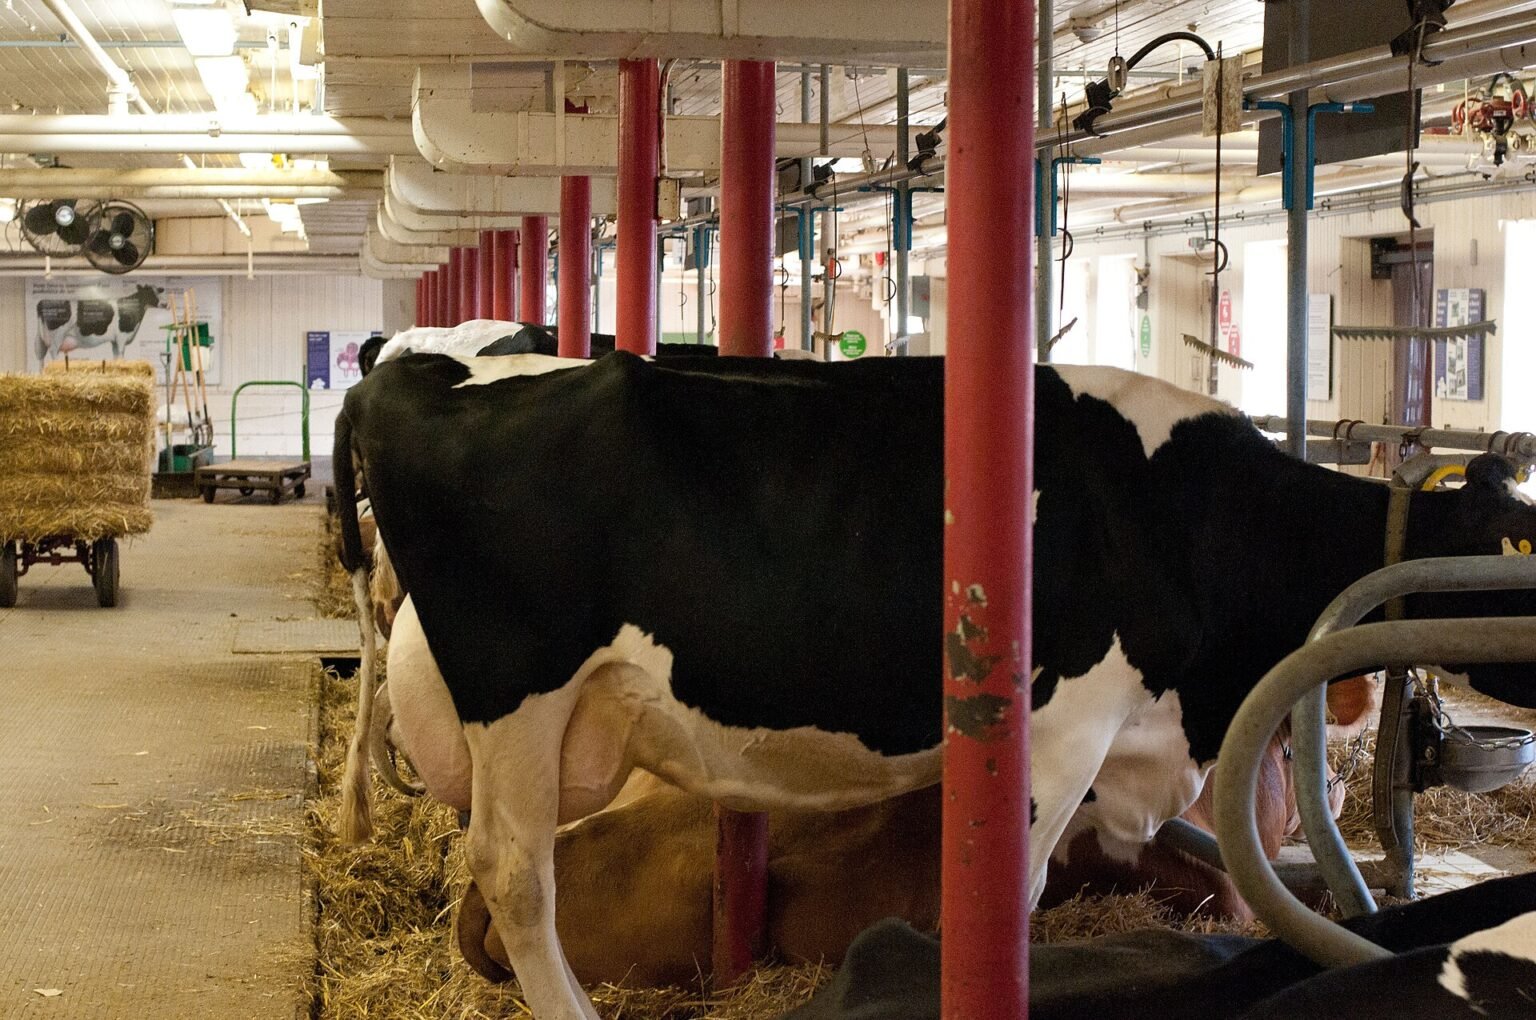
Washington will ban Canadian alcohol, dairy and motorcycles from 29 September

Dairy cows in a barn at the Central Experimental Farm in Ottawa, Ontario
Photo: M. Rehemtulla, CC BY 2.0, via Wikimedia Commons

01What happened

Hours after Canada’s counter-tariffs took effect on Monday 8 September, the White House announced that the United States will prohibit the import of certain Canadian alcoholic beverages, dairy products and large motorcycles from 29 September, using Section 338 of the Tariff Act of 1930. From 15 September, all-terrain vehicles and additional dairy products join the list of Canadian goods facing a 50% tariff, while rock salt and cement come off it. The administration also directed the U.S. Trade Representative and the General Services Administration to remove Canadian-origin products from federal purchasing schedules worth more than US$50 billion a year. A U.S. official said the products were chosen because Canada has little U.S. market share in them or because buyers can switch to other suppliers.

Ottawa’s counter-tariffs, at 15%, 25% and 50%, cover about $20 billion of U.S. goods. Prime Minister Mark Carney is due at the European Parliament on 16 and 17 September.

02Our view

We think the U.S. import ban is designed to be reversible in a negotiation, but we would not plan a business around it being reversed before 29 September. For the wider economy, it pushes the Bank of Canada toward a longer hold rather than a hike, even with oil above US$100.

Why we think so. The design gives it away. The White House will prohibit certain Canadian alcoholic beverages, dairy products and large motorcycles from 29 September under Section 338 of the Tariff Act of 1930, and a U.S. official said the products were chosen because Canada has little U.S. market share in them or because buyers can switch to other suppliers. Measures picked for their low cost to the side imposing them are also easy to withdraw, which makes them useful bargaining chips. At the same time, each round of this dispute is landing faster than the last, with only a week between Canada’s counter-tariffs and the U.S. reply. From 15 September, all-terrain vehicles and more dairy products face a 50% tariff while rock salt and cement come off the list, and U.S. federal purchasing schedules worth more than US$50 billion a year are to drop Canadian-origin products. A negotiation could reverse this, but nothing in the timetable suggests it will happen within three weeks.

The bigger picture. A ban is different from a tariff. A tariff makes a Canadian product dearer in the United States; a ban removes the market altogether. For distillers, wineries, dairy processors and their employees that is a revenue line falling to zero, not a squeeze on margins. For the economy as a whole, the effect arrives through the Canadian dollar, through provincial revenues in Ontario, Quebec and British Columbia, and through a central bank that now has to weigh a harder hit to growth against inflation from oil. A shock to growth of this kind makes a rate increase harder to justify, which is why we expect a longer hold.

What it means. A business owner with any U.S. sales should check both lists, the 15 September tariff additions and the 29 September ban, against their own product codes this week, and confirm what happens to goods already in transit on those dates. For an owner-manager, the planning question is continuity: how many months of fixed costs the company and the household could carry if U.S. revenue stopped on 29 September, and whether that runway is held in the business, personally, or nowhere. Households with concentrated exposure to one employer or one affected sector should hold more cash than usual this month. Borrowers should expect rates to stay where they are rather than rise or fall.

What would change our mind. An announced negotiation with a timetable before 29 September would make an early reversal of the ban likely. On the Bank of Canada, a Canadian August CPI print above 3% would put a hike back on the table despite the trade hit.

What to watch. The 15 September tariff additions and the 29 September ban, Prime Minister Mark Carney at the European Parliament on 16 and 17 September, the Federal Reserve on 16 September and the Bank of Canada on 29 October.

03Why it matters to you

If your business sells alcohol, dairy or motorcycles to the U.S., a ban removes the market rather than taxing it. Planning cash flow and new markets now limits the damage.

Book a business review

Sources The White House, Fact Sheet: President Donald J. Trump Responds to Canada’s Retaliation; Axios, Trump bans some Canadian imports as North America trade war intensifies; Transport Topics, U.S. bans dairy products, alcohol and motorcycles from Canada; Finance Canada, List of products from the United States subject to counter-tariffs effective September 8, 2026

Story 4 of 5

Asking rents fell 3.6% in a year, and Vancouver and Calgary fell the most

Rental apartment buildings in North Vancouver, British Columbia
Photo: Tristan Menzies, CC BY 3.0, via Wikimedia Commons

01What happened

Statistics Canada’s quarterly rent statistics for the second quarter, released Wednesday 9 September, put the average asking rent for a two-bedroom apartment across all census metropolitan areas at $2,130 a month, 3.6% lower than a year earlier. Asking rents fell 6.4% in Calgary and in Abbotsford-Mission, 5.2% in Montréal and 4.1% in Vancouver. They rose in smaller markets: Thunder Bay 6.5%, Sherbrooke 5.7%, Halifax 5.3% and Saskatoon 5.2%. Vancouver still has the highest asking rent at $3,030, followed by Toronto at $2,650, Victoria at $2,640 and Halifax at $2,400. In most cities the rent being asked for vacant units was above what sitting tenants pay; Calgary, Regina and Edmonton were the exceptions.

02Our view

We think the fall in asking rents is driven by supply rather than weak demand, which makes it more durable than a downturn-driven dip. We expect it to continue into 2027 in the large western and Quebec markets, keeping headline inflation lower than oil alone would suggest.

Why we think so. The pattern points to supply. Statistics Canada’s quarterly figures put the average asking rent for a two-bedroom apartment at $2,130 a month, 3.6% lower than a year earlier. The declines are concentrated where building has been strongest: asking rents fell 6.4% in Calgary and in Abbotsford-Mission, 5.2% in Montréal and 4.1% in Vancouver. In smaller markets with less new supply they rose: Thunder Bay 6.5%, Sherbrooke 5.7%, Halifax 5.3% and Saskatoon 5.2%. The detail on sitting tenants confirms it. In most cities the rent asked for vacant units is still above what existing tenants pay, but in Calgary, Regina and Edmonton it is below, the sign of a market where new supply has caught up with demand. A wave of completions meeting slower population growth does not reverse quickly, because buildings once finished stay on the market.

The bigger picture. Rent is a large part of the consumer price index, so a sustained decline offsets some of the inflation coming from energy. That matters for the Bank of Canada, because shelter costs have been one of the stickiest parts of inflation in recent years. A fall driven by supply also differs from one driven by recession: it comes with more homes, not fewer jobs, so it eases costs without the damage that usually accompanies falling prices.

What it means. Rent is the largest line in the budget of the roughly one in three Canadian households that rent. A renter whose lease is up in the next six months can price the neighbourhood before renewing; a 4% to 6% gap is worth a conversation with the landlord. For investors holding a rental condo, the rent assumed in a purchase from 2022 or 2023 is not the rent the market offers today, while the mortgage on that purchase may be renewing at a higher rate, so the cash flow should be rerun with both current figures. For would-be buyers, the case for buying instead of renting has weakened this year in exactly the cities where it was already thin. The comparison depends on how long you expect to stay and what the down payment would otherwise earn, with fixed rates in the low-4% range.

What would change our mind. Asking rents in Calgary, Vancouver and Montréal turning back up year over year, or declines spreading to the smaller markets where rents are now rising. The first would mean supply has been absorbed; the second would point to broad weakness in demand rather than a supply story.

What to watch. Friday’s Statistics Canada national balance sheet for the second quarter, which shows the value of household real estate, and the Bank of Canada’s 29 October decision.

03Why it matters to you

If you rent in Vancouver or Calgary, falling rents may give you room to negotiate or move. Putting the savings to work is worth a plan.

Book a budget and savings check

Sources Statistics Canada, The Daily: Quarterly rent statistics, second quarter 2026

Story 5 of 5

Reading tariff headlines as an investor: what 2025 taught, and what Canadians actually own

The Toronto Stock Exchange building in downtown Toronto
Photo: Halava, CC BY-SA 3.0, via Wikimedia Commons

01What happened

A management note from Equitable Asset Management Group dated 26 August, shared with the desk this week, makes a point worth setting beside this week’s escalation. Its figures: the U.S. 50% tariff of 22 August touched roughly 5% of the value of Canadian exports to the United States, more than 80% of those exports still cross duty-free under CUSMA, and the S&P/TSX Composite set a record high on 25 August, three days after the tariff took effect. It also recalls that in the 2025 tariff scare the U.S. market fell almost 20% between 19 February and 8 April 2025 and the Canadian market about 13%, before both recovered.

Statistics Canada added a related number this morning: Canada’s net foreign asset position rose by a record $619.2 billion in the second quarter to $1,945.5 billion, mostly because the foreign stocks Canadians own rose faster than Canadian ones. In the quarter U.S. equities gained 14.9%, European 13.6%, Japanese 37.2% and Canadian 6.4%, and about 70% of Canadians’ international assets are equities.

02Our view

We agree that headline risk and portfolio risk are different things, and that Canadian households have been quietly insulated from the tariff war. For the rest of this year, though, we think the larger risk in many portfolios is not tariffs but an unintended concentration in foreign equities.

Why we think so. The Equitable Asset Management Group note of 26 August makes the case well. By its figures, the U.S. 50% tariff of 22 August touched roughly 5% of the value of Canadian exports to the United States, more than 80% of those exports still cross duty-free under CUSMA, and the S&P/TSX Composite set a record high on 25 August, three days after the tariff took effect. Statistics Canada’s figures this morning show why households have been sheltered: Canada’s net foreign asset position rose by a record $619.2 billion in the second quarter to $1,945.5 billion, mostly because the foreign stocks Canadians own rose faster than Canadian ones. In the quarter U.S. equities gained 14.9%, European 13.6%, Japanese 37.2% and Canadian 6.4%, and about 70% of Canadians’ international assets are equities. The affected sectors are a small share of the index and a smaller share of what households actually hold.

How this has played out before. In the 2025 tariff scare the U.S. market fell almost 20% between 19 February and 8 April 2025 and the Canadian market about 13%, before both recovered. The investor who sold on the headlines missed the recovery; the investor who held a single distillery or dairy processor did not recover in the same way. The lesson is about diversification, not about optimism. Our caution is the flip side: a quarter in which foreign markets beat Canada by that margin also means many portfolios now hold more U.S. and foreign equity than they were designed to, at a moment when U.S. yields near 4.8% make bonds a genuine alternative.

What it means. For investors, the practical check is the share of the portfolio in Canadian equities, U.S. equities and other foreign equities today against the share it was meant to have. If the drift is more than 5 points of the total, that is a rebalancing decision. Where each holding sits, an RRSP, a TFSA or a taxable account, decides whether it costs tax to make: rebalancing inside registered accounts is free of tax, while trimming in a taxable account can trigger a capital gains bill. That bill is a cost; an unintended concentration is a risk. They are not the same category. A written target mix, checked on a schedule, takes the decision out of the headlines.

What would change our mind. A broad decline in the Canadian index on the scale of the 2025 episode, about 13%, driven by tariff news rather than rates. That would mean headline risk had become portfolio risk, and we would say so.

What to watch. Friday’s U.S. consumer price index and Statistics Canada’s national balance sheet for the second quarter, the Federal Reserve on 16 September, and the U.S. import ban on 29 September.

03Why it matters to you

If tariff headlines make you want to sell, what you actually own matters more than the news. A review shows how exposed your savings really are.

Book a portfolio review

Sources Equitable Asset Management Group, Management Update: Our view on the tariff situation (shared with the desk as a document image; URL to be confirmed); Statistics Canada, The Daily: Canada’s international investment position, second quarter 2026; TheStreet, Stock Market Today (Sept. 9, 2026): Dow, Russell 2000 fall as Brent passes $101/bbl; Treasury yields set new 52wk highs

Today’s news, considered against your own plans.

If one of these stories bears on your mortgage, savings, income or business, we would be glad to go through it with you and explain clearly what, if anything, it means for you.

Book a conversation

Free · optional

The Morning Brief in your inbox at 06:00 Pacific.

The day’s stories, what each means for you, and our view. Unsubscribe in one click.

Email subscriptions open shortly.